
ATM Cash Advance・Instant Money
- Rating
- 4.5
- Downloads
- 1.00M
- Content Rating
- Everyone
ATM Cash Advance・Instant Money - Screenshots
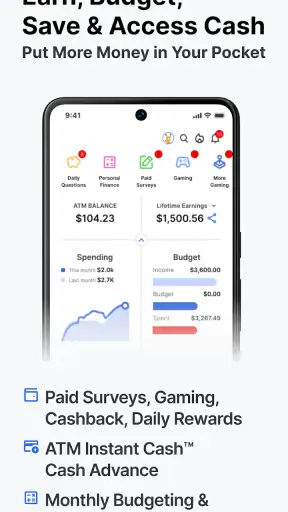
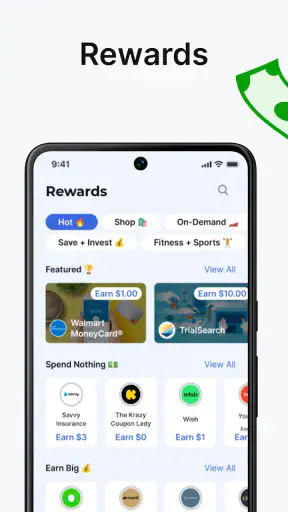
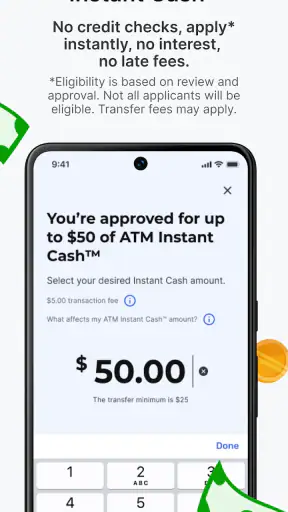
Pros
- Simple application process with clear steps for requesting an advance.
- May help cover urgent expenses before your next paycheck.
- Useful repayment and fee details are shown before confirmation.
- Convenient access from a smartphone without visiting a physical lender.
- Support resources can help users understand advance-related questions.
Cons
- Approval and advance amounts may vary based on your personal information.
- Fees or expedited-transfer charges can make borrowing more expensive.
- Repayment may be withdrawn automatically on the scheduled due date.
- Availability and terms can differ by state
- bank
- or eligibility profile.
- Late repayment could strain your budget and affect future access.
ATM Cash Advance・Instant Money - Description
- App Name
- ATM Cash Advance・Instant Money
- Package Name
- com.atm.atm.prod
- Developer
- ATM.com, Inc.
- Category
- Finance
- Last Updated
- Oct 26, 2020
- Version
- 2.140.0
When an unexpected expense lands between paydays, the difference between a useful finance app and a frustrating one is usually speed and clarity. ATM Cash Advance・Instant Money is built around that exact moment: it offers access to cash advances without a credit check, while also presenting itself as a way to save money through daily use. I reviewed it as a finance app rather than treating it like a replacement for a bank account, and my main impression is straightforward: its value depends on using the advance feature as a carefully controlled bridge, not as extra income.
The app is developed by ATM.com, Inc. and is free to install. It is rated for Everyone, runs on Android 8.0 or later, and its current version is 2.140.0. The store listing shows a 4.5 average from around 54 thousand ratings, with more than a million installs. Those figures suggest that the concept is easy for many people to understand, but popularity should not be confused with affordability in every situation. With any cash-advance service, I would still read the terms shown during the application process before accepting anything.
What the cash advance capability really changes
A bridge for timing problems, not a long-term financial plan
The central capability is the possibility of getting an instant cash advance without a credit check. That matters most when the problem is timing rather than income. A bill may be due before a paycheck arrives, a small household need may appear unexpectedly, or an ordinary purchase may become urgent. In those cases, the app can be more relevant than a traditional loan application that takes longer or depends heavily on a credit profile.
At the same time, “instant” should not make anyone treat the money as free or automatic. The practical question is not simply whether an advance is available. It is whether the amount, repayment timing, and any associated costs fit comfortably into the next budget cycle. I would open the app with a specific amount and purpose in mind, rather than browsing for money first and deciding what to do with it afterward.
This distinction is important because a cash advance solves a short gap. It does not remove the expense that created the gap, and it does not improve a budget that is already short every month. If I needed recurring help with rent, groceries, or debt payments, I would look for a broader budgeting or debt-support solution instead. ATM Cash Advance・Instant Money makes more sense when the need is occasional and clearly defined.
Why the lack of a credit check can be useful
A credit check can be a barrier for people with limited credit history or past financial difficulties. The app’s no-credit-check positioning makes it potentially useful for someone who might not qualify for a conventional credit product. That does not mean the advance is risk-free, and it does not mean approval or access should be assumed. It simply changes the first hurdle a user faces.
In my view, the strongest benefit is psychological as well as practical: the user can investigate a short-term option without beginning with a traditional credit application. But that convenience makes careful reading even more important. I would check the final amount received, the total amount to be repaid, the due date, and any optional or additional charges before confirming. If those details are not comfortable, I would close the application rather than rely on urgency to make the decision.
The saving angle needs a different mindset
The app also presents daily saving as part of its purpose. I see that as a secondary reason to keep using it, not as a justification for taking an advance. Saving tools are helpful when they turn a vague intention into a repeatable habit, but they cannot compensate for borrowing more than the next paycheck can support.
A sensible workflow is to separate the two ideas. I would use the saving side to build a small cushion during normal weeks, then consider the advance feature only if an unavoidable timing problem remains. Combining both habits can be useful: the savings activity reduces future emergencies, while the advance feature may handle a present one. Reversing that order—borrowing first and hoping to save later—is much less convincing.
How I would use it in practice
Starting with the reason and the repayment date
Before opening the advance screen, I would write down three things: what the money is for, how much is actually needed, and when the next dependable income arrives. This simple preparation prevents a common mistake with fast financial products: requesting a rounded amount instead of the smallest amount that solves the problem.
For example, imagine a utility payment is due two days before payday. I would compare the bill with the cash already available, request only the shortfall if the app allows that amount, and then check whether repayment would leave enough for food, transportation, and other fixed expenses. If repayment would create another shortage, the advance is not solving the problem; it is moving it a few days forward.
During the process, I would treat every confirmation screen as important. I would not rely on the headline amount alone, because the amount received and the amount repaid may not be identical. I would also save the repayment details somewhere I can find them later. That is a small but valuable habit, especially if several financial apps or automatic payments are already competing for attention.
Using the app during an everyday emergency
Here is the kind of situation where I think the app has a credible role. A person has a regular paycheck, but a necessary prescription or urgent transport cost appears just before payday. They do not want to apply for a conventional loan, and waiting could create a larger problem. They open the app, review the available advance terms, compare the repayment date with their paycheck, and take only the amount required.
The important part of that scenario is the discipline around the feature. The user is not using the money for an impulse purchase, a recurring subscription, or a bill that will still be unaffordable next month. They are using it to cross a short, identifiable gap. Once the paycheck arrives, they should confirm that repayment has occurred as expected and then consider directing a small amount toward savings so the same emergency is less disruptive next time.
A practical routine for the saving tools
I would approach the saving side in weekly reviews rather than checking it constantly. Once a week, I would look at what was saved, what upcoming expenses are likely, and whether the balance is becoming a genuine buffer. This turns the app from an emergency button into part of a larger routine.
One useful trade-off is to keep the savings goal modest at first. A target that leaves everyday essentials untouched is more sustainable than an ambitious amount that forces another advance. If the app offers daily saving prompts or actions in the current experience, I would use them as reminders, while still judging success by the money retained rather than by how often I open the app.
I would also avoid treating an in-app balance as interchangeable with money needed for immediate bills. Savings are useful only when they remain available for the purpose intended. If an advance repayment is approaching, I would prioritize understanding that obligation before moving money around for a less urgent goal.
What “instant” means from a user’s perspective
The word instant naturally creates an expectation that money will arrive immediately and without friction. In practice, I would distinguish between a quick application experience and the exact timing of funds becoming usable. The app may make the request process fast, but the final availability can still depend on the information requested and the delivery method shown during the process.
That is why I would not wait until the last possible minute if a bill has a firm deadline. I would review the available option early enough to understand the conditions and leave room for a different solution if the advance does not fit. Speed is valuable, but a rushed decision is rarely a good financial workflow.
The best scenario for this app
When a small, temporary gap is the whole problem
ATM Cash Advance・Instant Money is most persuasive for someone with predictable income who occasionally faces a short cash-flow mismatch. The person may not want a credit-based product, may need a relatively small bridge, and may be able to repay on the next reliable income date. In that narrow situation, avoiding a lengthy conventional application can be genuinely helpful.
I would be particularly comfortable recommending that a friend investigate it when the expense is necessary, the repayment source is already known, and the user has checked the total cost. The app’s free download also makes it easy to explore the available experience before deciding whether it belongs in a personal finance routine. Free installation, however, should not be read as free borrowing.
When the usual alternatives are better
If the need is predictable, a standard budget is usually better than an advance. Someone who knows that a yearly insurance payment is coming should set money aside ahead of time, use a dedicated savings account, or discuss a payment schedule with the provider. Borrowing repeatedly for a known bill adds pressure to each future payday.
If the amount needed is large or repayment will take several months, I would compare regulated lending options, credit-union products, or a structured payment plan instead. Those alternatives may involve more paperwork, but they can be easier to understand when the financial need is not temporary. Likewise, if the issue is high-interest debt, a debt counselor or a consolidation comparison may be more appropriate than another short-term advance.
The app is also not the best fit for someone who has no dependable repayment date. Without that anchor, the speed of access becomes a weakness. A person who is already using advances to cover previous advances should pause and seek a longer-term solution rather than adding another transaction.
Trade-offs I noticed before recommending it
Convenience can encourage overuse
The same easy access that helps during a genuine emergency can make borrowing feel ordinary. This is the main behavioral risk. A user may begin with one necessary advance, then use the app for convenience purchases because the process feels less serious than a traditional loan application.
My practical safeguard would be to create a personal rule: only use the feature for an expense that would cause a real problem if delayed, and never use it to increase discretionary spending. I would also record each advance outside the app, including the reason and repayment date. That extra record makes patterns visible. If the list grows, the correct response is to reassess the budget, not simply to request less each time.
The total cost matters more than the headline promise
A no-credit-check advance can sound attractive before the user sees the full repayment terms. I would judge the product by the complete cost and timing shown for my own request, not by the store summary. Even a small charge can matter when the budget is tight, and an optional service or expedited method may change the final amount.
This is where ATM Cash Advance・Instant Money should be compared with the alternatives available to the individual. A bank overdraft, a family loan, an employer advance, or a payment extension may be cheaper in a particular case, although each carries its own conditions and risks. The app is useful when its terms are clearer or more practical for the situation—not simply because it is faster to open.
Eligibility and access should be checked before planning around it
The app’s description makes the no-credit-check feature prominent, but that should not be interpreted as a promise that every user will receive every amount or that every request will be completed identically. I would treat the amount and conditions displayed inside the app as the only basis for a decision. Until those details are visible, I would not count the money as part of a bill-paying plan.
This is a subtle but important planning point. If a payment is due today, I would first contact the biller, use existing funds, or ask a trusted person about alternatives rather than assuming an app-based advance will arrive in time. The app can be part of the backup plan, but it should not be the only plan when the consequence of delay is serious.
Privacy and attention deserve consideration
Finance apps require a higher level of attention than ordinary utility apps because the information and decisions involved are sensitive. I would review the permissions and privacy explanations presented during setup, use a strong device lock, and avoid checking financial details on a shared phone. I would also keep notifications useful rather than allowing every prompt to drive spending decisions.
That last point connects to the saving experience. Reminders can support a habit, but frequent financial prompts can also make the app feel like something that must be acted on immediately. I prefer to choose a regular review time and make decisions when calm. The best outcome comes from using the app deliberately, not from responding to every notification.
Who gains the most from the experience
A good match for occasional, controlled use
I think the strongest audience is someone who has regular income, understands their upcoming cash flow, and wants a fast way to investigate a short-term advance without a credit check. That person can benefit from the app’s focused design while keeping the advance separate from normal spending.
It may also suit a user who wants to build a saving habit alongside emergency access. The combination is more useful than either feature alone when the user treats savings as prevention and advances as an exception. In that role, the app can help someone become more aware of the difference between a temporary timing issue and a genuinely unbalanced budget.
A poor match for ongoing financial strain
I would advise caution for anyone whose income is unpredictable, whose essential expenses already exceed income, or who is carrying several short-term obligations. The app may provide immediate relief, but immediate relief can become a repeating cycle when there is no realistic repayment room.
I would also steer away from it for impulse spending, entertainment, shopping upgrades, or recurring bills that are permanently too high. Those uses do not benefit from speed; they need a spending change, a negotiated payment arrangement, or a more durable financial product. A different budgeting app may be better for identifying leaks, while a bank or credit union may be better for planned borrowing.
My final recommendation
ATM Cash Advance・Instant Money has a clear and useful purpose: it gives users a way to explore a fast cash advance without a credit check, while pairing that emergency function with saving-oriented tools. I appreciate the focus because it addresses a real problem—being short at the wrong moment—without pretending that borrowing is the same as earning.
My recommendation is conditional but positive. I would suggest trying it to a friend who has a specific urgent expense, a dependable repayment date, and the patience to inspect the full terms before accepting. I would not recommend treating it as a standing extension of a paycheck. The smartest way to use this app is to make the advance the exception and the savings habit the long-term goal.
As a free finance app from ATM.com, Inc., with an Everyone age rating and support for Android 8.0 and newer, it is accessible to a broad audience. Its real value, though, is not the download itself or the promise of speed. It is the decision-making structure a careful user brings to it: borrow only for a defined gap, confirm what repayment will require, and use the saving side to make that gap less likely in the future.
FAQ
What is ATM Cash Advance・Instant Money, and how does it work?
ATM Cash Advance・Instant Money is a financial app designed to help eligible users explore short-term cash advance options through a mobile device. After creating an account, you may be asked to provide personal, identity, employment, and banking information. The app may then connect you with potential lenders or financial service providers. Approval, available amounts, fees, and repayment terms depend on your profile and the provider’s assessment.
Can I receive money instantly after applying through the app?
Despite the “instant money” wording, funding is not necessarily immediate for every applicant. The application may be reviewed first, and additional verification could be required before a decision is made. If approved, delivery time can depend on the lender, your bank, weekends, holidays, and the selected transfer method. Always review the estimated funding time and confirm when repayment begins before accepting an offer.
What fees, interest, or repayment costs should I expect?
The total cost can vary significantly depending on the offer presented to you. Possible charges may include interest, origination fees, service fees, late-payment penalties, or other costs disclosed by the lender. Before agreeing to anything, check the annual percentage rate, finance charge, total repayment amount, due date, and consequences of missing a payment. Never rely only on the advertised advance amount.
What information does ATM Cash Advance・Instant Money require?
To evaluate an application, the service may request details such as your name, address, date of birth, income, employment information, identification, bank account details, and contact information. Because financial data is sensitive, read the privacy policy and permissions carefully before submitting anything. Make sure you understand whether your information is shared with lending partners, marketing providers, or other third parties.
Is ATM Cash Advance・Instant Money available to everyone?
Availability depends on factors such as your location, age, income, banking status, credit profile, and the requirements of participating providers. Downloading the app does not guarantee approval or access to a cash advance. Some users may receive no offers, while others may qualify for different amounts or terms. Check the app’s eligibility rules and local regulations, and borrow only what you can repay on time.


